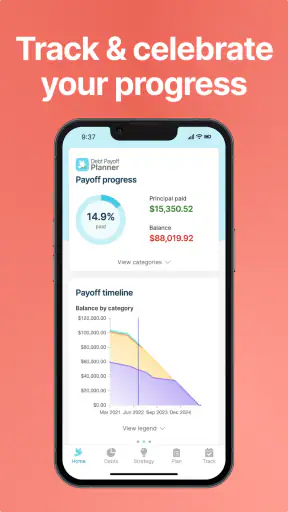
Debt Payoff Planner & Tracker is the kind of finance app I would recommend to someone who feels that debt is difficult mainly because it is hard to see the whole picture. Rather than trying to be a complete banking replacement, it focuses on turning balances, payments, and deadlines into a plan you can follow. In my experience, that narrow purpose is its biggest strength: it gives debt repayment a visible structure instead of leaving everything scattered across statements, notes, and memory.
The app is free to install, with optional in-app purchases priced from $6.99 to $41.99 per item. It comes from Easily get a plan and stick to it - OxbowSoft LLC, carries an Everyone age rating, and has been available since January 8, 2015. With a 4.5 average from around 4.7 thousand ratings and more than 500 thousand installs, it has clearly attracted a substantial audience without presenting itself as a complicated financial suite.
How Debt Payoff Planner & Tracker works in everyday use
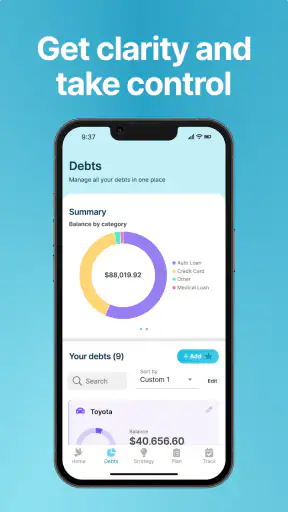
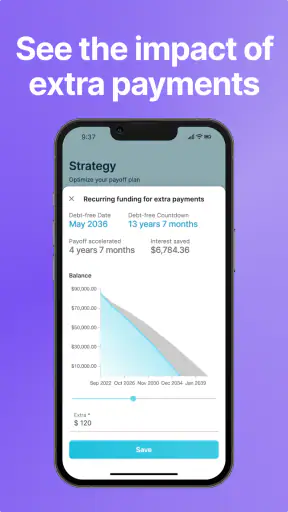
The first useful shift is psychological. Most people know they owe money, but knowing the total is not the same as knowing what to do next. A debt planner can help separate the problem into individual accounts and repayment steps. That makes it easier to answer practical questions such as which balance deserves attention first, how long a chosen strategy may take, and what happens when an extra payment is added.
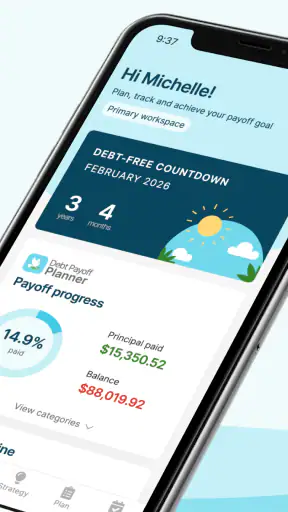
I find this approach more helpful than a simple balance list. A list tells me where I stand today; a payoff plan gives me a reason to check again next week. That distinction matters because debt reduction is usually a repeated habit rather than a one-time calculation. The app’s central promise is not instant financial rescue. It is a way to plan, track progress, and make the act of paying debt feel measurable.
For a first setup, I would gather recent statements before entering anything. The important details are the current balance, minimum payment, interest information, and payment timing for each debt. Entering rough figures may produce a plan that looks reassuring but does not match reality. This is one of the less obvious lessons of using a dedicated planner: the quality of the result depends heavily on the quality of the starting information.
Once the accounts are organized, I would use the app as a monthly checkpoint rather than opening it only when I feel anxious. After making payments, update the relevant balances and compare the new position with the previous one. That routine turns repayment into a record of decisions. It also exposes small problems early, such as a balance that is barely moving or a payment that was lower than intended.
Why a visible strategy is more useful than general budgeting
Budgeting apps are often better at showing where money goes. They can categorize groceries, transport, subscriptions, and other spending, but they may not make the debt itself feel like a project with milestones. Debt Payoff Planner & Tracker is more focused. I would use it alongside a budget, not instead of one, because a payoff schedule can tell me what I want to pay while a budget tells me whether that amount is actually available.
This separation is valuable for people who already have a spreadsheet or banking app for everyday spending. The planner does not need to replace those tools. It can act as the debt-specific layer: one place for balances, repayment order, and progress. That is a better fit than forcing an all-in-one finance app to handle a goal it was not designed to emphasize.
The trade-off is that users looking for automatic financial organization may find the experience more hands-on. A dedicated payoff tracker is most useful when I am willing to enter information, review it, and keep it current. If I want every account and transaction to update without my involvement, a connected banking service may feel more convenient.
The repayment strategy needs personal judgement
A plan is not automatically good simply because it is mathematically tidy. I would consider whether the proposed order keeps me motivated, whether minimum payments remain covered, and whether the plan leaves enough room for essentials and unexpected costs. A strategy that demands every spare dollar can fail after one car repair or medical bill. The app can organize the repayment goal, but it cannot decide how much financial breathing room my household needs.
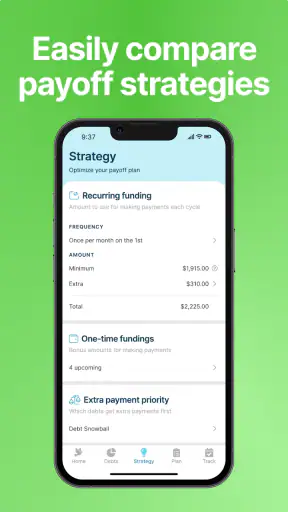
One practical method is to create a conservative plan first. I would use an extra-payment amount that I can maintain even in an ordinary difficult month, then treat unusually strong months as opportunities for additional progress. This is more sustainable than building a schedule around an optimistic income assumption. It also makes the tracker a test of consistency rather than a source of guilt.
Another useful workflow is to compare two possible approaches before committing emotionally to one. For example, I might prefer the fastest visible win if a small balance can be cleared quickly, while someone else may care more about reducing costly interest. The important point is to understand the trade-off and choose deliberately. A payoff planner is at its best when it supports that decision instead of encouraging me to follow a number blindly.
A realistic household scenario
Imagine a household with a credit card balance, a personal loan, and a store account. The minimum payments are manageable individually, but the family keeps losing track of which account should receive extra money. At the start of the month, they enter the current figures and choose an amount that can be reserved after rent, food, utilities, and transport. During the month, they make the required payments and direct the planned extra amount to the selected target.
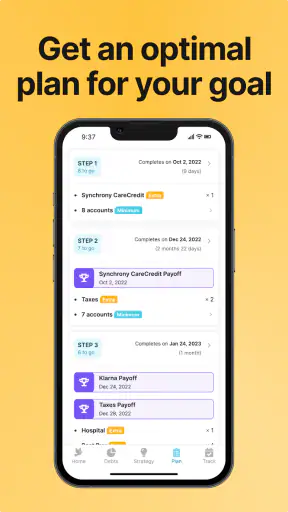
At the next review, the household updates the balances rather than relying on memory. If the credit card has not dropped as expected, that may reveal interest, a new purchase, or a missed assumption in the original plan. If the target balance is shrinking, the progress becomes a reason to continue. When one account is cleared, the amount previously used there can be redirected to the next account instead of disappearing into casual spending.
That last step is where a tracker can become genuinely useful. Paying off one account is satisfying, but the long-term benefit comes from preserving the payment habit. I would treat each cleared balance as a transfer of momentum, not as permission to loosen the plan immediately. The app’s value is therefore less about a dramatic first calculation and more about helping the user maintain a sequence of decisions.
Where the app is strongest
The strongest part of this app is its focus. It does not ask me to manage investments, monitor every purchase, or learn a large financial dashboard before I can address debt. For a person whose main concern is repayment order and progress, that reduced scope can make the task less intimidating. A focused tool is often easier to revisit than a feature-heavy money platform.
I also appreciate the motivational side of tracking. Debt repayment can feel invisible because the reward arrives slowly. A progress view gives the user something concrete to revisit, especially after a payment that would otherwise feel like money simply leaving the account. That emotional reinforcement is not a substitute for accurate figures, but it can help turn a good intention into a repeated monthly action.
The app’s long availability is another reassuring sign for someone choosing a focused tool. It was released on January 8, 2015, and the current version is 2.54. I would still keep my own statements as the authoritative record, but the established history makes it feel less like a short-lived experiment and more like a product built around a continuing use case.
What requires patience and care
The main weakness is the manual responsibility that comes with a planner. If balances change and I do not update them, the projected path becomes less useful. Interest, fees, new charges, payment timing, and promotional terms can all affect the real outcome. I would never treat the app’s schedule as a lender statement or financial guarantee. It is a planning aid, and its accuracy depends on regular maintenance.
That limitation is especially important for people with complicated debt. Variable rates, changing minimum payments, shared accounts, or frequent new borrowing can make a clean payoff plan harder to maintain. In those cases, I would use the app as a simplified overview while checking the detailed terms directly with each lender. Someone who needs tax planning, credit monitoring, or professional debt advice should look beyond this app.
There is also a motivational risk. Seeing a long repayment path can encourage some users, but it may discourage others, particularly when progress is slow at the beginning. I would avoid checking it obsessively or interpreting every month as a pass-or-fail test. A better habit is to review it on a fixed schedule, record what changed, and adjust the plan when circumstances genuinely change.
The optional purchase model is worth considering before committing to the app as a long-term tool. The download is free, but in-app items range from $6.99 to $41.99. I would first establish whether the free experience fits my workflow, then decide whether any paid element offers enough practical value for my situation. A purchase should make the planning process more useful, not become another expense added to an already tight budget.
Who should use it, and who should choose something else
I think this app is a strong match for someone with several debts who wants a dedicated repayment plan without building a spreadsheet from scratch. It is also suitable for users who are motivated by visible progress and are comfortable entering updates themselves. A person starting a debt payoff journey may find the focused design less overwhelming than a broad personal-finance platform.
It can also work well for couples or families who need a shared conversation starter, even if they keep their banking arrangements separate. Sitting down with the current balances and a chosen extra-payment amount can make the plan more concrete. I would make sure everyone agrees on the figures and update routine, because a tracker is only helpful when the household treats it as a common reference rather than one person’s private guess.
I would be more cautious about recommending it to someone who expects automatic account synchronization, detailed spending analysis, or complete financial management in one place. A banking app may be better for transaction visibility, while a spreadsheet may be better for unusual debt structures and custom formulas. If the debt situation involves collection activity, legal pressure, or an inability to meet minimum payments, a nonprofit counselor or qualified adviser may be more appropriate than any tracking app.
Users on older phones should also check compatibility before installing. The app requires Android 6.0 or later, so it is not aimed at every legacy device. It is listed as an app in the Finance category and is rated for Everyone, which makes it broadly approachable, but the subject matter itself is still adult financial responsibility. Younger users may need help understanding interest, minimum payments, and the difference between a projection and a promise.
My practical setup advice
I would begin with a short preparation session rather than rushing through the first screen. Collect the latest figures, label each debt clearly, and decide whether the plan is based on minimum payments plus a fixed extra amount or on a more flexible monthly contribution. If one account has an unusual rate or fee, note that separately so it does not get lost in a simple balance comparison.
Next, I would set a review date that matches the household’s normal money routine, such as shortly after payday or after statements arrive. The goal is not to interact with the app every day. A regular review is enough for most people and reduces the chance that the tracker becomes another source of financial stress. During each review, compare the planned payment with the actual payment and ask why they differ before changing the entire strategy.
Finally, I would keep a small emergency buffer outside the payoff amount whenever possible. This may slow the projected finish, but it can prevent a minor surprise from forcing new borrowing. That is a trade-off the app cannot make for me. The best plan is not always the fastest theoretical plan; it is the one I can continue without repeatedly undoing progress.
Overall, Debt Payoff Planner & Tracker succeeds because it treats debt as a sequence of manageable actions rather than an abstract total. Its focused design, progress-oriented approach, and free entry point make it appealing for people who want structure without a full financial suite. The cost is hands-on upkeep, and the projections should be treated as planning guidance rather than exact promises.
My recommendation is clear: use it if your main need is a dedicated payoff roadmap and you are willing to keep the numbers current. Pair it with your bank statements and a realistic budget, and it can provide the motivation that ordinary account screens often lack. Skip it in favor of a more connected finance tool, a custom spreadsheet, or professional guidance if your priority is automation, complex analysis, or help with unaffordable payments. For the right user, the best feature is the discipline of returning to a visible plan, not the novelty of another money app.
With its 500K+ installs, free starting price, Everyone rating, and current version 2.54, it is an accessible option for a focused debt project. I would not install it expecting it to solve the financial problem on its own. I would install it expecting a practical place to turn repayment into a routine—and, for many people, that is exactly the part of the process that has been missing.


